Date: 20 November 2026
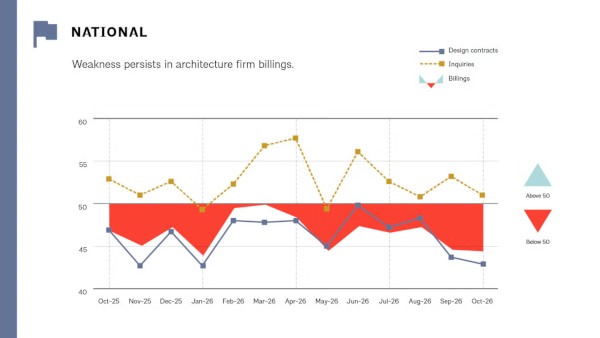
The AIA/Deltek Architecture Billings Index® (ABI) score remained well below 50 at 44.9 for the month, as billings have not been in consistently positive territory for more than four years now. While this does not mean that business is soft at every firm, it means that billings continue to decline from one month to the next at a majority of firms. Inquiries into new projects increased again in October, as clients remain interested in starting projects, but the pace of that increase slowed from September. And despite inquiries from potential clients, the value of newly signed design contracts remains weak as it continues to decline like billings.
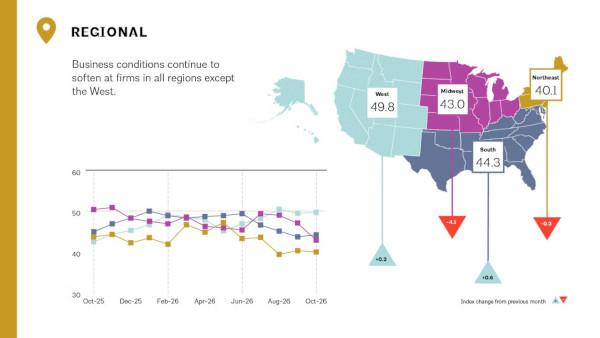
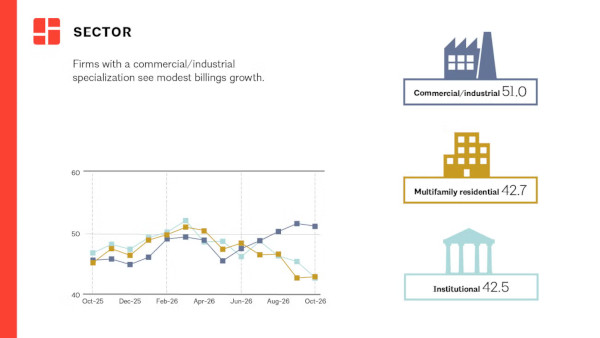
Business conditions were also soft at firms in all regions of the country in October. For the fourth consecutive month, they were weakest at firms located in the Northeast, although they have also softened further at firms located in the Midwest and South in recent months. However, billings were essentially flat at firms located in the West for the third consecutive month, which is encouraging. By firm specialization, billings increased for the second consecutive month at firms with a commercial/industrial specialization. This marks the first period of growth at these firms since 2022. However, after showing some signs of improvement at the beginning of the year, billings have softened significantly at firms with institutional and multifamily residential specializations this fall.
Broader economy shows job gains as inflation eases
Despite soft conditions in the architecture industry, conditions in the broader economy were more encouraging in October. Total nonfarm payroll employment grew by 165,000 new positions, well above the recent monthly average of 48,000, while the unemployment rate remained low at 4.1%. Architectural services employment added 100 new jobs in September (the most recent data available), for a total of 204,000 employed in the industry. This is 900 positions higher than the June low.
Inflation also softened modestly in October, with the Consumer Price Index (CPI) rising by 0.4%, after increasing by 0.6% in September. The largest contributor to the slower growth rate was stabilization in energy prices: energy prices overall increased by 0.7% (after increasing by 5.2% in September, while gasoline prices rose by 1.0%, down from 9.1% in September. However, food prices increased by 0.5% in October after they were flat in September.
Most firms report billings from activities that aren’t intended to result in design or construction activity directly
In this month’s special practice questions, we asked architecture firm leaders about recent billings at their firms derived from activities that weren’t intended to result in design or construction activity directly. Overall, responding firm leaders reported that an average of about 9.7% of their firm billings over the last year were from activities that weren’t intended to result in design or construction activity directly. While 14% of responding firm leaders reported that they had no billings from this type of work, 11% reported that 20% or more of their billings came from this work, with 2% reporting that it accounted for 50% or more of their billings. Small firms with annual billings of less than $250,000, firms located in the Northeast, and firms with an institutional specialization reported the highest shares of billings from this type of work, at an average of 14.3%, 11.2%, and 10.3%, respectively.
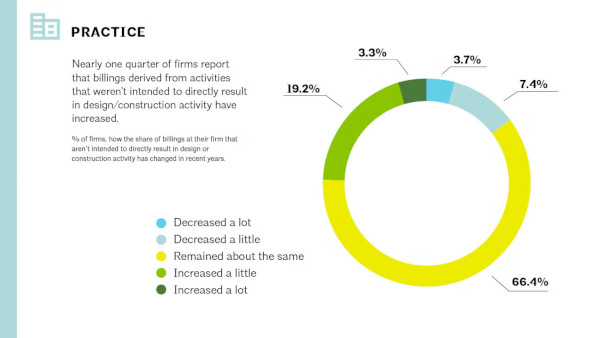
When asked how the share of billings derived from activities that weren’t intended to result in design or construction activity has changed in recent years, nearly one quarter of responding firm leaders (23%) reported that it had increased, while 66% said that it had remained about the same, and 11% said that it had decreased. Firms located in the Northeast were least likely to report that this share had increased (13%) and were most likely to report that the share had decreased (18%).
When asked specifically which services are not among standard design services their firm provides, by far the most frequently selected type, by 83% of respondents, was planning and pre-design services. This was followed by non-design/construction consulting services (24%), owner representative services (20%), research studies and application (19%), environmental consulting services (8%), and building operation and maintenance services (5%). In addition, 9% indicated that their firm doesn’t provide non-standard design services. When asked to select which type of non-traditional design services is the primary one offered by their firm, nearly three-quarters (74%) selected planning and pre-design services, with just 5% each selecting owner representative services and non-design/construction consulting services. However, 12% of small firms with annual billings of less than $250,000 selected owner representative services, and 11% of firms with a multifamily residential specialization selected non-design/construction consulting services.
- Rewatch our AIAU webinar, Economic Update: Q4 2026 ABI Insights.
 600450

Add new comment