Date: 17 September 2026
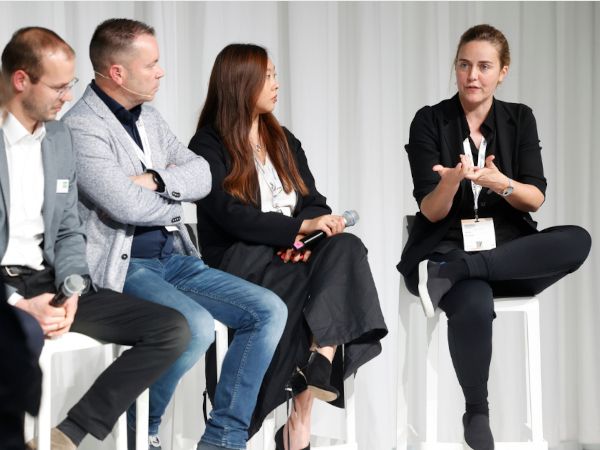
At glasstec 2024, Sophie Pennetier presented her team’s work on circular glass logistics in California. Centrestage is the question of how disassembled architectural glass can be kept away from landfills and returned to manufacturers as a raw material. Her experience of the political, commercial and regulatory frameworks in this field primarily relate to the US market.
At glasstec 2024 you presented your team’s developments in the area of circular glass products. Why does post-consumer architectural glass so often end up in building rubble instead of being reintroduced into the material cycle?
At Digne we work along the entire glass-decarbonisation chain – from circularity logistics that separate and reroute disassembled glass towards ongoing projects, to the development of innovative glass products that increase its value. The idea is to treat disassembled glass as a supply stream rather than rubble and to link construction sites with the manufacturers who can make use of it.
We are based in California and every conversation about glass circularity needs to take into account just how much the US varies from state to state – especially in terms of policy framework, business structures, minimum wages that can vary by a factor of ten, approval procedures and landfill costs. The background conditions change as soon as you cross a state border.
Today, when glass does not make its way back into the circular economy it’s not for technical reasons; it’s down to business as usual and logistical reasons. The old assumption that tempered safety glass and laminated glass cannot be recycled is outdated. Even the PVB interlayer can be reclaimed. But there are nuances: impurities such as ceramic frit and enamel do not pose any problems to produce abrasive blast media from recovered glass but complicate logistics for the float-glass, driving up significant risk and costs which most often exclude this path entirely. I recently met a float glass producer where minimal impurity shut down a line for a whole week: flat glass worth one to two million was rerouted to a lower quality usage. Add to this the schedule impacts and risk for future production runs. Closed cycles bear significant risks which require high-stakes conversations early on in a recovery project.
Besides the primary risks the remaining obstacles are costs and timing. Handling glass separately from contaminants is more expensive for demolition contractors than wrecking a building at once. This represents a line item that owners rarely include in their budgets but combined with landfill costs and the receiver project procurement costs, net out at the end of the day, without even leveraging the social cost of carbon. General contractors engaged in both the donor and receiver projects had the strongest circularity success on our projects. Architects also play an important role: priorities such as the embodied carbon of construction materials or recycling content are not typically stated in the scope of work unless the project is aiming at LEED certification and are often in conflict with the budget and timeline. With one of our projects the timeline – rather than the costs – got in the way of a procurement of a lower carbon material option. Our aim is to be faster, cheaper and better but until we get there, we will always have to balance all risks.
Who in the supply chain has to rethink first: architect, façade contractor, glass processor or demolition contractors?
The first step needs to be taken by the building owner and designers responsible for demolition. In practice, they direct general contractors and demolition subcontractors and need to have those conversations before the bid. Communication doesn’t cost anything and yet it’s the most difficult thing on a project. You decide from the outset that glass is sorted in a clean-grade way, include it in the contract for the subcontractors and find a recycler. If the owner and their design teams fail to do this for the bid not even the best of intentions will help to save the material later. It’s the building owner and their consultants who assess whether a building can be disassembled at all. Processors are constantly expanding their technical capabilities but the fate of the glass is already decided at the planning stage prior to demolition.
Beyond this, it takes persistence. We have introduced three recyclers to our demolition partner and it has taken us several years. Thanks to our joint persistence, however, the city-wide recovery project has now started. This is not just flicking a switch but a relationship you build.
Do we need new standards to recognise recycled post-consumer glass as a certified building material or is it already covered by existing test methods?
Yes, we need new standards but their development will take years and be drawn from pilots. I’ve witnessed this with ASTM and other professional associations first hand. I prefer spending my time on leading the pilots that drive these standards rather than waiting for a committee to negotiate a consensus. Standards work both ways: they can drive a whole industry but if they are too narrowly defined, they can prevent the gradual progress that will get us there in the first place. The bigger challenge isn’t a lack of testing but market acceptance and logistics: building a market based on its own evidence rather than on changing funding and fluctuating interest. The reclaimed material streams are already being incorporated into established processes with their own specifications: glass fiber insulation, sandblasting media, carpet backing and PVB-based products such as paints, fibers, and adhesives. Clearer standards would give planners, in particular, more assurance for setting out requirements for recycled content and for ensuring consistency in the supporting documentation for certification programs such as LEED.
Local jobs, critical raw material procurement sovereignty, reduced dependency on imports are positive outcome of a circular economy. This is both a commercial and an ecological argument.
I’ve lobbied jointly with professional associations. These efforts confirmed which topics move Washington: votes, affordability and jobs. When considered with these aspects in mind, circular economy gains widespread support. Standards are developing slowly. Now the risks associated with implementation have to be minimised and the existing, untapped market needs to be verified.
Is there an aspect of your work that deserves more attention in the public debate about circularity in the construction sector?
The fact that the circular economy depends on unglamorous operational details rather than groundbreaking technology: smaller units, skilled staff, clearly labelled containers and discussions that are held before rather than after demolition. The results are tangible: we are in talks with a major event in our region to leverage significant amount of strict glass reuse, growing sales of the upcycled glass products developed by my team at Digne, and on the upstream recycling front here in LA we have channelled over 150 US tons of glass to recycling/reuse and are well on track to exceed 300 tons in the first year of post-consumer glass reclamation program. This surpasses New York’s results in the first year. We are very grateful for NY’s pioneering role, which accelerated our consistent yet slowed efforts. And they are on course to increase their recycling ratio tenfold next year provided projects run as planned. A little competition between the Coasts never hurts especially when a mission is so important.
In 2026 Sophie Pennetier will again feature as a speaker at glasstec,
this time at CircuClarity Two.
CircuClarity Two
CircuClarity Two is accessible free of charge for trade fair visitors as part of the glasstec conference. The conference will be held on Stage 3 of the “glass technology live” area in Hall 11 on 20 and 21 October 2026. The complete programme is available as of now at the glasstec Event database.
 600450

Add new comment